








Key Takeaways:
- A Gold 401(k) is a retirement strategy that links 401(k) savings to gold, often via a rollover into a self-directed Gold IRA.
- Moving 401(k) money into a Gold IRA without penalties typically requires a specific rollover or transfer process.
- You need to understand plan rules, tax obligations, required timing, which gold products are eligible, and account setup before making any major account moves.
A Gold 401(k) may sound like a workplace retirement plan that holds gold, but in reality, most traditional 401(k) plans offer limited account options, and many don’t allow clients to acquire gold directly inside the plan.
When someone talks about moving a 401(k) into gold, they often mean rolling eligible 401(k) funds into a self-directed Gold IRA. That process can be done without penalties as long as it follows IRS rules and the plan allows it. In this guide, you’ll learn how a Gold 401(k) works, how to move funds properly, and what American Hartford Gold has to offer.
How Does a Gold 401(k) Work?
Some workplace plans may offer gold-related fund options, but most don’t offer direct access to gold. That’s why many individuals consider a rollover from a 401(k) into a self-directed Gold IRA.
A standard 401(k) is sponsored by an employer and has to follow plan rules.
Those rules control when money can leave the plan, what account choices are available, and whether in-service rollovers are allowed. A former employer’s 401(k) may be easier to roll over than an active employer plan. Current workers may need to check whether their plan allows an in-service distribution.
Clearing Up Confusion
The phrase “Gold 401(k)” often creates confusion because it sounds like gold is sitting directly inside a workplace 401(k). That isn’t typically the case. A person may hold a gold-related fund in a 401(k) or roll over funds into a Gold IRA.
A Gold IRA is an account that allows eligible gold to be held within a self-directed retirement account. That makes it different from many employer-sponsored plans. A client who wants to acquire gold this way typically needs to understand whether a rollover is available. Your plan provider can help you understand what your 401(k) allows.
An old 401(k), a current 401(k), a traditional IRA, and a Roth account may each have different rules. Once the account type is clear, the next step is to determine which type of move is permitted under the rules.
How Does a 401(k) Rollover Into Gold Work?
A rollover moves eligible retirement funds from one retirement account to another. When someone wants gold exposure via a retirement account, the approach is often a self-directed Gold IRA. A proper rollover will preserve the status of the money.
If handled correctly, the move typically doesn’t create a taxable event. If handled incorrectly, the money may become taxable, and early distribution penalties may apply. There are two common ways to move retirement funds.
A direct rollover sends money from the 401(k) plan to the receiving retirement account. An indirect rollover sends the money to the account owner first, and the owner then has 60 days to place it into another eligible retirement account. Direct rollovers are often viewed as the better choice because the client doesn’t take control of the funds, which lowers risk.
The rollover process begins by opening the destination account, and then the client requests the move from the 401(k) plan. The plan may require forms, identity verification, certain details, and instructions for where the funds should go. Once the funds arrive, the client can work through the process to acquire qualifying gold products.
Direct Rollovers vs Indirect Rollovers
A direct rollover can lower tax risk because the funds move from one retirement account to another. The check may be made payable to the receiving account for the benefit of the client, or the funds may move electronically. The client never touches the money.
For an indirect rollover, the IRS gives you 60 days to roll it into another eligible retirement account. If the deadline is missed, the amount may be treated as taxable income. If you are under 59½, an additional penalty may also apply unless there is an exception.
With indirect rollovers from employer plans, withholding can also complicate matters. You may have to replace withheld funds from another source to roll over the full amount. If you don’t replace the withheld amount, that portion may count as a distribution. This is why most people prefer a direct rollover.
How To Move 401(k) Money Without Penalties
Many people can roll over an old 401(k) after leaving a job. Current employer plans may be more restrictive. Some plans allow in-service rollovers after a certain age. If you take money out of a 401(k) as a cash distribution before age 59½, you may owe income tax and trigger an additional early distribution penalty unless an exception applies.
Taxes can also vary based on account type. Moving pretax 401(k) money into a traditional IRA may allow you to keep the same tax situation. Moving pretax money into a Roth account may create taxable income because Roth accounts are treated differently for tax purposes. Clients need to establish whether the destination account matches the current account type.
Common Penalty Triggers
One mistake is cashing out a 401(k). A cash distribution may result in a tax penalty if the recipient isn’t eligible for an exception. It can also lower your retirement savings. A rollover keeps the money inside the retirement account structure.
Another mistake is missing the 60-day deadline on an indirect rollover. The IRS starts the timer from the date the distribution is received. If the funds don’t reach another eligible retirement account in time, the rollover could fail and trigger a penalty.
A third mistake is moving funds before confirming the plan’s rules. Some individuals assume every 401(k) has the same terms, which isn’t the case.
Gold’s Limitations in a Retirement Account
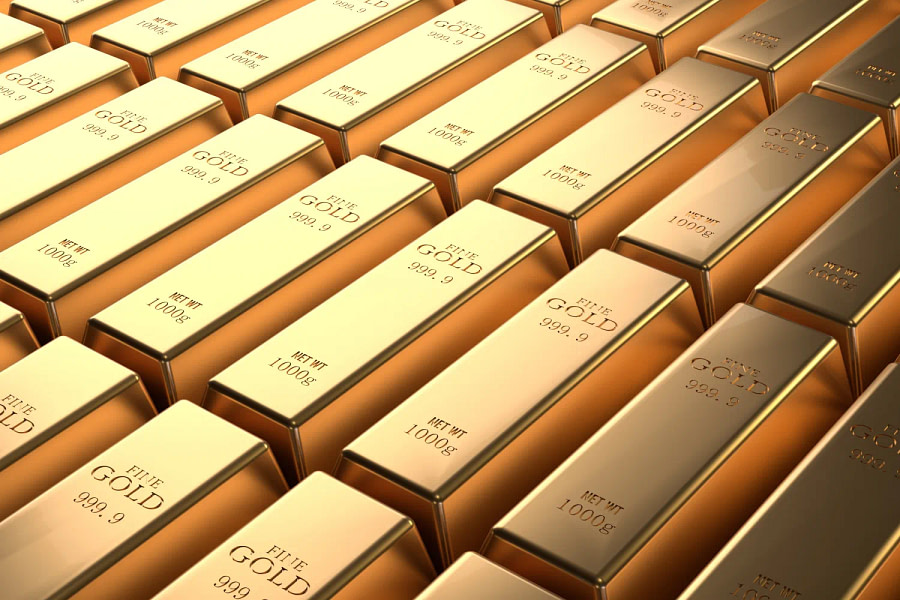
Gold has a long history as a reliable way to preserve wealth. A Gold IRA can include eligible gold, but not every gold coin or bar qualifies. IRS rules limit certain collectibles and set standards for metals held in IRAs.
That means clients need to research which products are eligible for the account before purchasing. Gold also doesn’t generate income by itself. Individuals shouldn’t treat it as a guaranteed payout. Instead, its purpose is long-term asset diversification.
Gold Product Eligibility
Gold for an IRA has to meet certain rules. Some coins and bars may qualify, but collectible items normally don’t. Gold from the U.S. Mint may be allowed when it meets the required standards.
It’s also important to avoid mixing personal purchases with IRA assets. Gold acquired for personal ownership isn’t the same as gold acquired through a retirement account. A Gold IRA follows its own rules and process.
Acquire Gold for Retirement With AHG
The best path to a Gold 401(k) begins with understanding your plan’s rules, selecting the right rollover method, and avoiding actions that may trigger penalties. A Gold IRA is a self-directed retirement account that can include qualifying gold and other precious metals under IRA rules.
American Hartford Gold offers a Gold IRA option for clients who are interested in exploring additional ways to diversify ahead of retirement or who are considering gold or silver ownership. Our dedicated team is ready to help you meet your goals today.
FAQs
What is a Gold 401(k)?
A Gold 401(k) is a common term for a retirement savings account linked to gold. In most cases, it doesn’t mean a workplace 401(k) directly holds gold. It normally means moving eligible 401(k) funds into a self-directed Gold IRA.
Can I move my 401(k) into gold without penalties?
You may be able to move eligible 401(k) funds into a Gold IRA without penalties when you use a proper rollover process and follow IRS and plan rules. A direct rollover is often the better path because the funds move from one retirement account to another without touching your hands. Cashing out the account can generate additional tax obligations and penalties.
What is the 60-day rollover rule?
The 60-day rollover rule applies when you receive retirement funds and then roll them into another eligible retirement account. You have 60 days from receiving the distribution to complete the rollover. Missing the deadline may result in the amount being treated as taxable income and triggering a penalty.
Does every 401(k) allow a rollover into a Gold IRA?
No, not every 401(k) allows a rollover into a Gold IRA. Old employer plans are often easier to roll over, while current employer plans may have restrictions. You need to check your plan’s distribution rules before initiating the process.
What kind of gold can a Gold IRA hold?
A Gold IRA can hold eligible gold that meets IRA and IRS rules. Not every coin, bar, or collectible item qualifies. Clients should confirm eligibility before acquiring gold for their account.
Sources:
Direct Rollover: What It Is and How It Works | Investopedia
Indirect Rollover: Definition, Rules, and Requirements | Investopedia
Retirement topics – Exceptions to tax on early distributions | IRS


